A clear monthly plan can help you manage your salary with greater intention.
introduction
Getting your salary every month can feel rewarding. But earning money is only one part of financial management. manage your salary by Knowing how to organize your income, control spending, save consistently, and plan for future goals is equally important.
Many people don’t struggle because they earn nothing. They struggle because their salary disappears before they understand where it went.
The good news is that managing your salary doesn’t have to be complicated.
You don’t need a perfect financial system or a complicated spreadsheet. A few simple rules, followed consistently every month, can help you become more intentional with your money.
Here are 08 simple rules to manage your salary better every month.
1. Know Your Take-Home Salary
Start with the amount that actually reaches your bank account each month.
Your salary package or gross income may be different from your take-home pay because of taxes, deductions, insurance, or other contributions.
Use your actual take-home income as the starting point for your monthly plan.
Once you know the amount available to you, it becomes easier to decide how much can reasonably go toward expenses, savings, and other financial priorities.
2. Plan Your Money Before You Start Spending
Don’t wait until the end of the month to see what is left.
As soon as your salary arrives, make a simple plan.
Write down:
•Essential expenses
•Savings
•Debt or loan payments, if applicable
•Personal spending
•Financial goals
A budget doesn’t need to be complicated. Its main purpose is to give every part of your income a clear purpose.
For more guidance, you can learn about creating a budget through Consumer.gov.
https://consumer.gov/your-money/making-budget?utm_
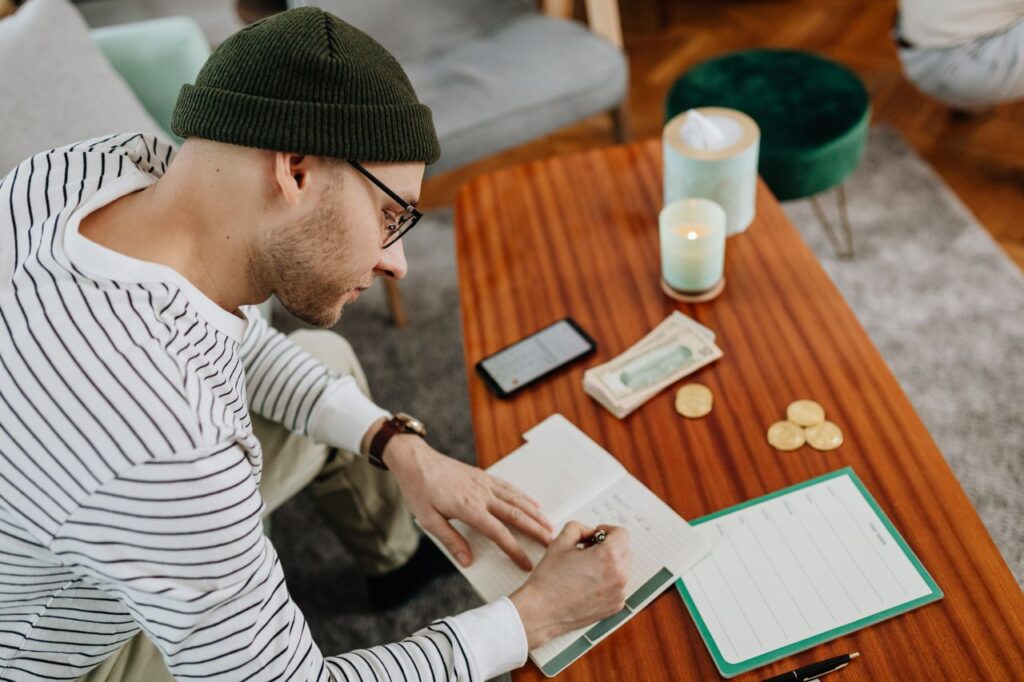
Planning your money before spending can give every part of your salary a purpose.
3. Save Before Your Money Disappears
One common mistake is spending first and saving whatever remains.
Instead, decide on a realistic savings amount at the beginning of the month.
If practical, transfer that amount to a separate savings account soon after receiving your salary.
The exact amount depends on your income, expenses, responsibilities, and financial goals. The important part is building a consistent habit rather than choosing an unrealistic target.
You can also read more about building better money habits in my article, 10 Money Habits That Can Make You Financially Stronger.
https://sandeepblogging.com/10-money-habits-that-can-make-you-financially-stronger/
4. Separate Needs From Wants
Not every expense has the same priority.
Needs may include:
•Rent or housing
•Groceries
•Utilities
•Transportation
•Essential healthcare
•Required payments
Wants may include:
•Eating out
•Entertainment
•Shopping
•Upgrading gadgets
•Unplanned online purchases
You don’t have to eliminate wants completely
The goal is to make sure your wants don’t regularly interfere with your essential expenses and financial goals.
5. Control Lifestyle Inflation
When your salary increases, it can be tempting to increase your spending immediately.
A bigger salary can lead to a bigger phone, more expensive restaurants, more shopping, or a more expensive lifestyle.
Instead, consider directing part of an income increase toward savings or important financial goals.
Enjoying some lifestyle improvements is reasonable. The important thing is not allowing every increase in income to automatically become an increase in expenses.
For more practical saving ideas, see 10 Smart Ways to Save Money Without Feeling Restricted.
https://sandeepblogging.com/10-smart-ways-to-save-money-without-feeling-restricted/
6. Keep an Emergency Fund Goal
Your monthly salary should not only support today’s expenses. Some of your financial planning should prepare you for unexpected situations.
An emergency fund can provide a financial buffer for unexpected expenses.
Start with a realistic target and build it gradually according to your circumstances.
You can learn more about emergency funds from
https://www.consumerfinance.gov/an-essential-guide-to-building-an-emergency-fund/?utm_
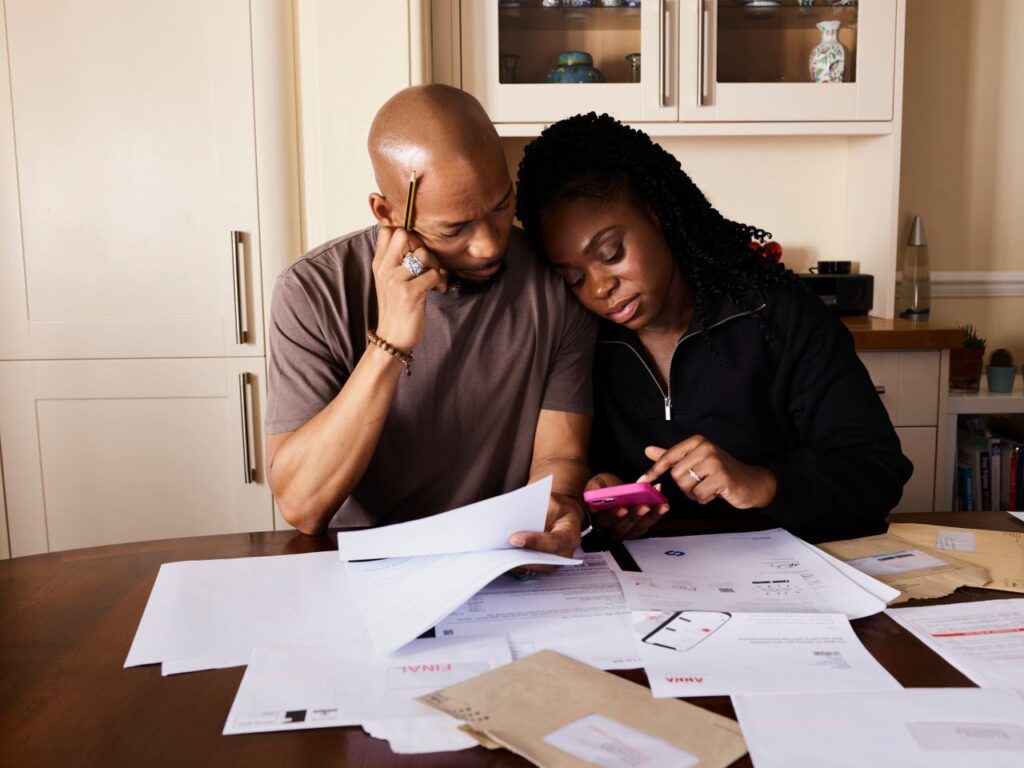
Regularly tracking expenses helps you understand where your salary is going.
7. Be Careful With EMIs and Credit
Before taking on a new EMI or using credit for a purchase, understand the total repayment obligation.
Ask yourself:
•Is this purchase necessary?
•Can I comfortably manage the payment?
•What is the total cost?
•Will this payment reduce my ability to save?
•Am I taking the credit because I need the item or because I want it immediately?
Credit can be useful in some situations, but regular borrowing for unnecessary purchases can make monthly cash flow more difficult.
https://www.consumerfinance.gov/an-essential-guide-to-building-an-emergency-fund/?utm_